
Free products can feel like one of the perks of being a content creator. A brand sends you clothes, cosmetics, technology, a hotel stay or even a trip. No money reaches your bank account, so it is easy to assume there is nothing to report.
But does “gifted” mean tax-free?
Not always. If you receive a product or service in return for promoting a brand, its value may count as business income. The position depends on why you received it, what the brand expected in return and how the arrangement connects to your work as a creator.
When a gifted product may be taxable
A product is likely to be connected to your business if a brand gives it to you in return for a service.
The brand might expect you to:
- publish a post, video or story;
- review or demonstrate the product;
- include a link or discount code;
- attend an event;
- mention the brand to your audience;
- produce user-generated content;
- meet an agreed deadline; or
- allow the brand to reuse your content.
If so, the product may be payment for your work. This is sometimes called payment in kind or a barter arrangement.
No cash has reached your bank account, but you have still received something of value for providing a service. HMRC’s guidance for online content creators says that business income includes the value of gifts or services received from promoting products online.
An example: products in return for content
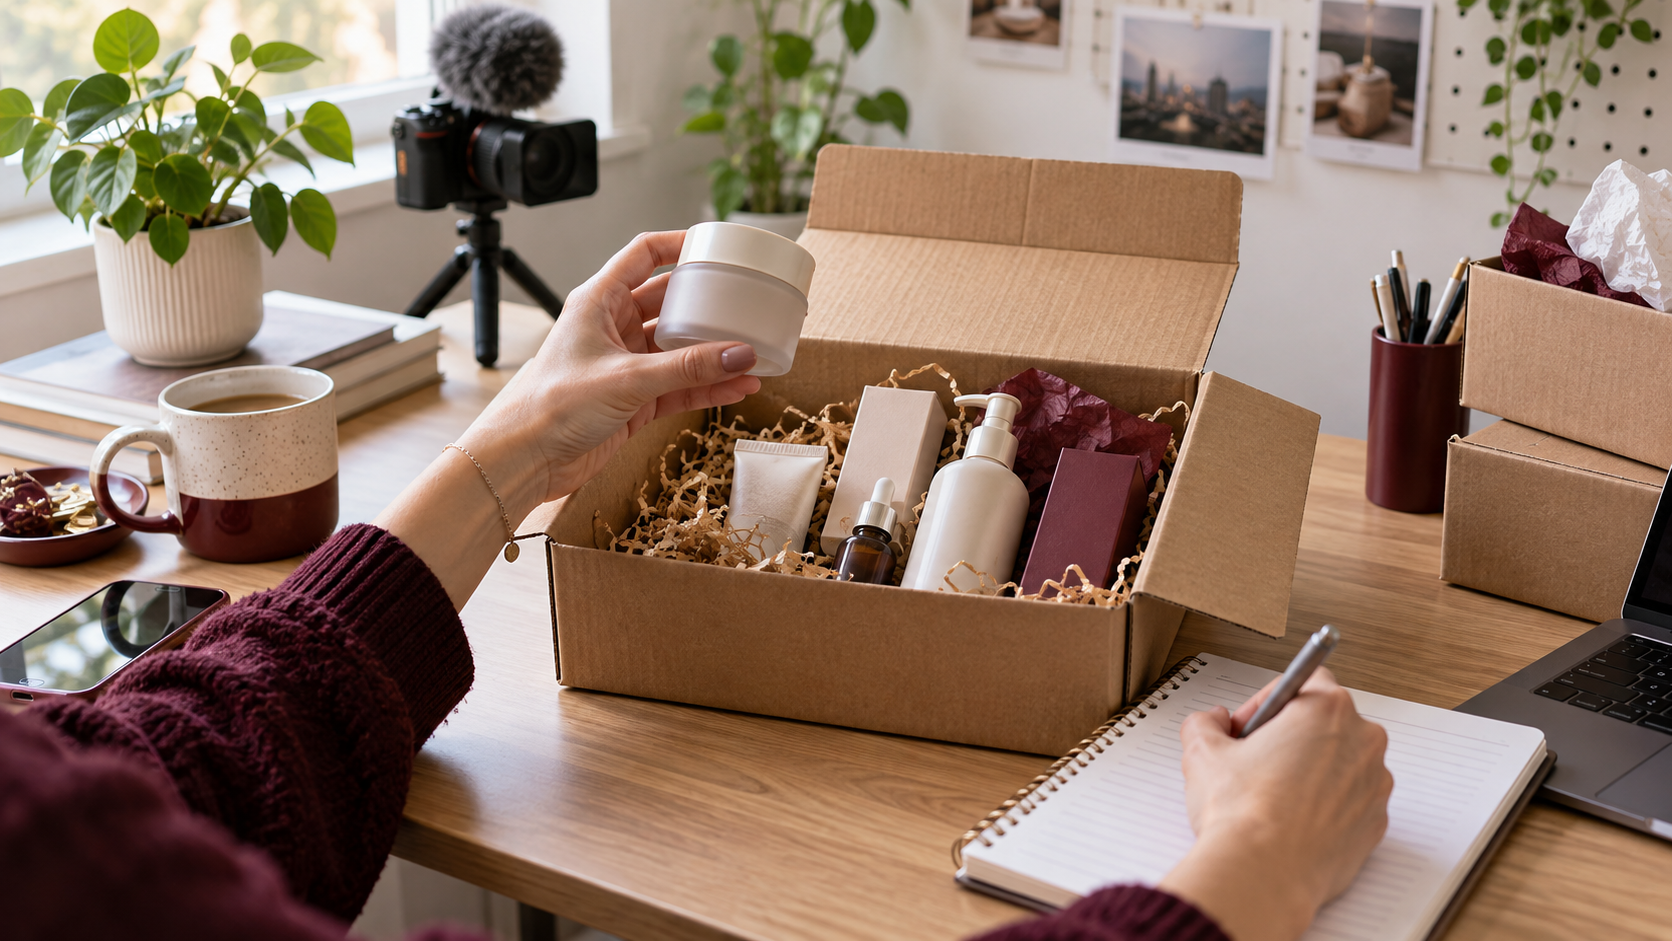
Suppose a skincare company gives an influencer products worth £500.
In return, the influencer agrees to create:
- one Instagram Reel;
- three Instagram Stories; and
- a link to the company’s website.
The influencer has not received cash, but they have provided marketing services in exchange for the products. The value received may therefore need to be included in the creator’s business income.
The creator should keep the agreement, relevant emails or direct messages, a list of the products and evidence of the value used in their records.
What about genuinely unsolicited gifts?
The position may be different if a brand sends you something without asking for content or placing you under any obligation.
Perhaps a PR package arrives that you did not request. The brand does not require a post, you have not promised anything and there is no agreement about how you will use the product.
An unsolicited item is not automatically payment for a service. However, the facts still need to be considered. Ask:
- Why did the brand send the item?
- Was there a formal or informal understanding?
- Do you regularly receive similar products as part of your creator business?
- Did you later agree to promote it?
- Was it a reward for earlier work?
- Did the brand expect something commercially valuable in return?
The label used by the brand is not decisive. Calling something “PR”, “complimentary” or “gifted” does not, by itself, determine its tax treatment.
What matters is the real arrangement and whether the item was received in return for, or as a reward for, your work.
How should you value a gifted product?
If a product is payment for your services, you need a reasonable and supportable value for your records.
Useful evidence may include:
- the value stated in the agreement;
- the normal selling price when you received it;
- the price shown on the brand’s website;
- an invoice or statement from the brand;
- details of any restrictions placed on the product; and
- evidence that you had to return it.
Do not automatically use an unrealistic recommended retail price if the item is normally sold for much less. The appropriate value can depend on the agreement and the circumstances, so keep the evidence supporting the figure you use.
If you receive a package containing several items, make a simple list of what was included and how each item was valued.
What if you do not want the product?
You may still have received something of value, even if the product is not something you would have chosen to buy.
Ask:
- Did you accept it as payment for your work?
- Were you allowed to keep, use, sell or give it away?
- Did you return it to the brand?
- Did the contract place a value on it?
An item loaned for filming and then returned is not the same as an item you are allowed to keep. Keep the loan or return terms with your campaign records.
Can you claim an expense for the product?
Recording the value of a product as income does not automatically mean you can claim the same amount as an expense. The answer depends on what happens to the product, how it is used and whether you are a sole trader or operate through a limited company.
For example:
- a cost incurred wholly and exclusively for the business may qualify for tax relief;
- an item kept for personal use does not automatically create an equal business deduction;
- mixed business and personal use may need an adjustment;
- equipment kept and used in the business may be dealt with under the cash-basis or capital-allowance rules, depending on the circumstances; and
- products held as stock for resale may need different treatment.
Do not assume the income and expense will cancel each other out. Sometimes they may. Sometimes they will not.
Do gifted products affect VAT?
They can.
If you provide promotional services in return for goods or services, the arrangement may amount to a barter transaction for VAT. HMRC treats non-monetary consideration as capable of including goods or services supplied as payment.
If you are not VAT registered, the value of any taxable UK supplies you make through barter arrangements may need to be included when monitoring the VAT registration threshold. The compulsory registration threshold is £90,000 of VAT taxable turnover in a rolling 12-month period at the date this article was reviewed.
If you are VAT registered, you may need to account for output VAT on the value of your supply, even though the brand paid you with a product or experience rather than cash.
The precise treatment depends on matters including:
- what each party agreed to supply;
- the value of the consideration;
- whether you were allowed to keep the item;
- where the customer belongs; and
- the VAT liability and place of supply of the service.
This last point matters when you work with overseas brands or agencies. A service that is outside the scope of UK VAT should not automatically be treated as UK VAT taxable turnover simply because a product was delivered to you in the UK.
A genuinely unsolicited product, with no service provided in return, should not automatically be treated in the same way as an agreed product-for-content arrangement.
What about free hotel stays, meals and trips?
The same principles can apply to experiences and services. The issue is not limited to physical products.
You might receive:
- complimentary hotel accommodation;
- restaurant meals;
- flights or other transport;
- event tickets;
- spa treatments;
- holidays or press trips; or
- free memberships and subscriptions.
If you agree to create content or provide another commercial service in return, the value you receive may form part of the business arrangement.
Travel needs particular care. Creating content during a trip does not automatically make every related cost allowable for tax. Private enjoyment, family members travelling with you or extending the trip for a holiday can all affect the position.
What records should you keep?
A simple gifted-products register can save a great deal of confusion later.
For each product or experience, record:
- the date you received it;
- the brand or agency involved;
- what you received;
- its agreed or estimated value;
- whether content was required;
- the deliverables you agreed to provide;
- whether you kept or returned the item;
- how you used it;
- the related contract, email or direct message;
- links or screenshots of the published content; and
- any notes about its tax or VAT treatment.
This gives your accountant enough information to separate commercial arrangements from genuinely unsolicited items. It also means you are not trying to reconstruct everything months later from old messages and half-remembered conversations.
Common mistakes
Creators often run into problems because they:
- assume anything described as “gifted” is tax-free;
- record cash payments but ignore payment in kind;
- delete campaign messages and agreements;
- use no value, or an unsupported value, for products;
- assume the income and expense will always cancel each other out;
- forget about free stays, meals and experiences;
- overlook the VAT position; or
- mix personal products with genuine business costs.
A useful question to ask
Whenever you receive a product, ask yourself:
Would the brand have given me this if I were not a content creator, and what did it expect from me in return?
That question will not settle every case. But it is a useful starting point when deciding whether you received a genuine gift or entered into a commercial arrangement.
How Capshine can help
Gifted products are easy to miss because they do not appear as deposits in your bank account.
If they are not recorded correctly, your accounts may be incomplete. You could also face an unexpected tax bill or find that your VAT taxable turnover is higher than you thought.
Capshine works with UK content creators and social media influencers. We can help you:
- review gifted-product and barter arrangements;
- decide what should be recorded;
- work out a reasonable value;
- separate business and personal use;
- monitor VAT taxable turnover;
- set up a simple gifted-products register; and
- understand the treatment without the jargon.
If you regularly receive PR packages, complimentary experiences or products in return for content, book a free creator tax check with Capshine. We will help you work out what needs to be recorded and what evidence you should keep.
This article provides general information only. The tax and VAT treatment depends on the agreement and the individual circumstances. Please obtain professional advice for your particular position.
Last reviewed: September 2026